
Practical Strategies to Increase Your Credit Card Limit
How do you actually increase your credit card limit? Start by using the right channel and making sure your income and account details are current. Use the card regularly, then pay on time. The issuer sets the starting limit and reviews future increases based on its own assessment. In some cases, authorized-user cards or other accounts with the same issuer can also increase your total spending capacity.
Key takeaways
- The initial limit is based on a risk assessment, and customers with similar incomes may start with different amounts.
- Your payment restores available credit only after the payment is processed, so your available balance does not return immediately in every case.
- Data from the Central Bank of Brazil shows that a significant share of users utilize more than 99% of their limit, while fewer than 5% move into revolving credit.
- If your request is denied, it makes more sense to update your income information, adjust how you use the card, and wait for the next review window than to submit another request immediately.
- An authorized-user card and products with secured credit limits do not work like a traditional limit increase because they follow different rules for available credit or collateral.
How Your Credit Card Limit Is Set When You’re Approved
Your starting limit usually comes from a risk assessment, not a universal formula. The issuer may review your reported income, payment history, relationship with the bank, and signals from your credit profile. That’s why two customers earning similar incomes can receive very different starting limits.
Credit card apps often show three figures that are easy to mix up: your total credit limit, available credit, and credit already committed. Once a purchase is approved, your available credit falls right away, even if the charge won’t appear on the statement until later. After you pay, the available amount returns only when the transaction is processed.
The Central Bank of Brazil reports in its “Credit Card Usage Profile in Brazil” section that credit-limit utilization varies widely based on a user’s relationships with financial institutions. The report also says that a significant share of people use nearly all of their available credit, above 99%. It records low movement into revolving credit, below 5%, which helps explain why issuers watch customer behavior closely before approving more credit. Central Bank of Brazil
With an authorized-user card or multiple relationships with the same issuer, your available spending capacity may change because the issuer manages the credit limit on a consolidated basis. An extra card doesn’t create new money. It usually shifts the same spending capacity between cards according to the issuer’s rules.
How to Request a Credit Limit Increase and Which Channels Are Usually Available
- Open the issuer’s app or banking super app and look for the cards, credit limit, financial services, or limit-increase section. At many banks, this is the fastest way to submit a request without speaking to a representative.
- If the issuer has a customer service center, call the official number on the back of your card to ask about a credit limit increase. Some issuers may also handle this type of request at a branch, but that is not universal.
- Before submitting your request, check that your income information is up to date, your account details are consistent, and you have used the card recently. A request submitted with outdated information is generally less likely to move forward smoothly.
- After you submit the request, the issuer conducts a new review, and the response time varies by issuer and channel. For example, Inter’s customer support information says that some requests submitted through the Super App may receive a response within 7 days, while other issuers simply state that a review will follow without setting a standard timeframe.
Itaú Cartões tells customers to search the app for the credit-limit-increase option, choose the command related to the limit, and then select the card and requested amount. For Inter, the request is also available in the Super App, and its customer support information says the response may take up to 7 days. The pattern is common: you can usually make the request in the app, although the menu name differs from one bank to another. Itaú Cards
Some issuers offer products with a secured credit limit, including certain PagBank options. In those cases, an increase may depend on how much you invest or on the collateral tied to the product. That’s a related situation, but it follows a different path from a traditional increase based on a credit review.
What to do when your increase is denied
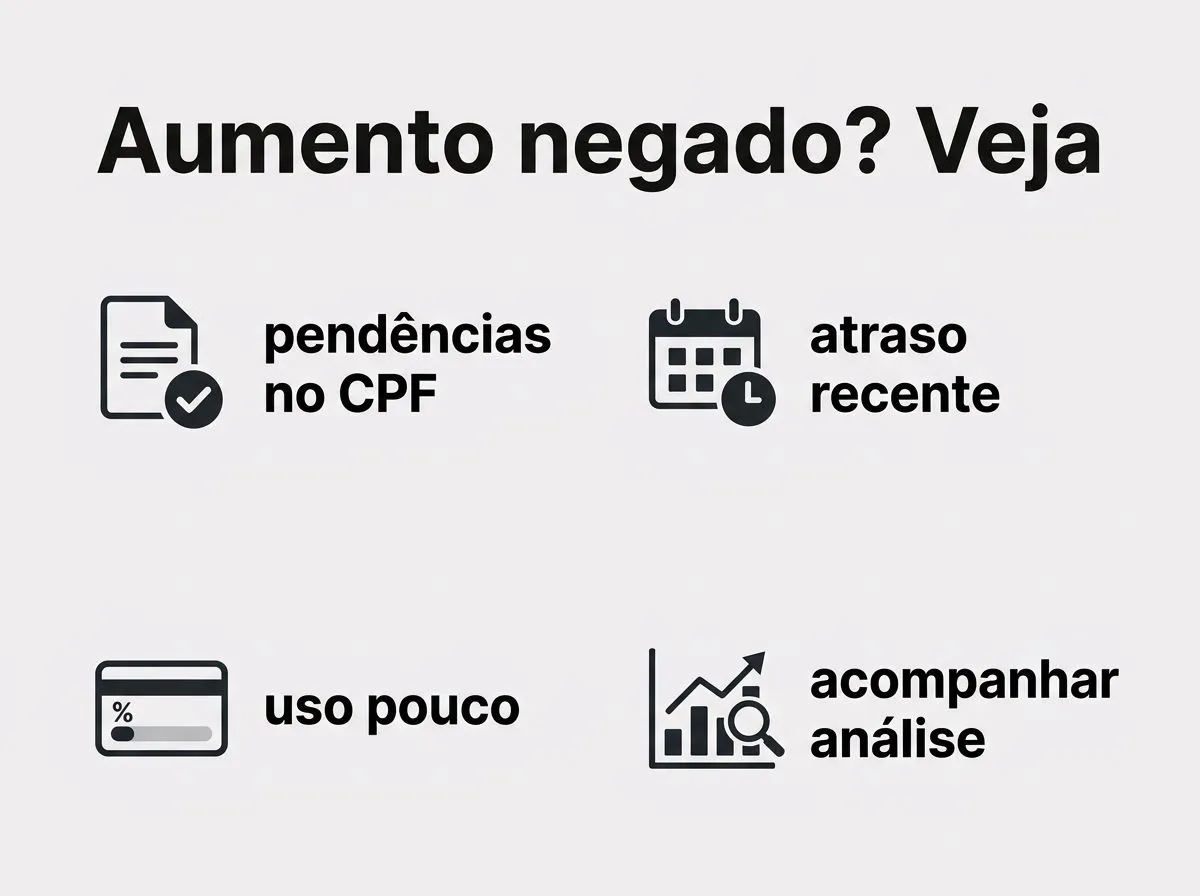
- Check for outstanding issues linked to your CPF, a recent late payment, or another risk signal in your history. These factors can weigh against approval, even when your income appears sufficient.
- Consider whether you use the card very little or very irregularly. Without much activity, the issuer receives fewer positive signals about your ability to pay.
- Compare the requested amount with the income you reported. Requests that exceed what your income can support are more likely to be denied.
- Wait for the next review window and adjust your profile before trying again. Repeatedly requesting an increase without making any changes usually only leads to another denial.
- Update your income and account information through the official channel, and use the card responsibly by always paying on time. This can help build a more favorable history for the next review.
Inter says it evaluates requests using internal criteria and lets customers track the review in the Super App. The practical takeaway is that a denial isn’t necessarily permanent. Usually, it means that something in your information worked against the request at that time. Before trying again, you’ll need to change or strengthen that factor. Inter
Editorial guidance from VLV Advogados lists the length of your relationship with the institution and your financial stability among the factors that may be considered. The bank’s own policy still controls the decision, but this helps explain why an on-time payer can be denied. Paying correctly matters, but it is only one part of the review. VLV Advogados
How purchases, statements, and credit limit usage work in practice
An approved purchase reduces your available credit immediately, even when the charge won’t show up on your next statement until later. It may sound like a small detail, but it changes how you should read the app. Your available credit falls when the transaction is authorized, not when the payment is due.
Paying your statement restores available credit after the bank processes the payment. If you make the payment today, the limit may not come back that same minute. Don’t assume the amount is instantly ready for another large purchase.
Installment purchases also reduce your available credit because the transaction reserves part of the limit until the installments are paid, according to the issuer’s policy. Revolving credit works differently. It applies when you fail to pay the statement in full by the due date. The Central Bank says the maximum revolving-credit period is 30 days before the debt may move to another type of financing, under the rule cited in the Central Bank’s credit card accumulated-interest panel.
Using a large share of your credit limit for long stretches can make your statements harder to manage and may send a less favorable signal during future reviews. The Central Bank’s study of usage patterns shows that users with multiple credit relationships tend to commit a smaller share of their maximum limit. That suggests they have more room to adjust across their credit accounts. Central Bank of Brazil
What to look for in your credit limit behavior to improve your next review
| Observation criterion | What your card usage indicates | How this helps with your next review | What not to misinterpret |
|---|---|---|---|
| Consistent usage | Frequent purchases that fit your income | Shows real activity and recent history | Don't confuse frequent use with high debt |
| On-time payments | Statement paid by or before the due date | Reduces risk signals and improves your payment history | Paying only the minimum is not the same as paying off the statement |
| Keeping your information up to date | Income and personal information consistent in the app | Gives the issuer a better basis for recalculating your limit | Outdated information can hurt how your profile is assessed |
| Credit limit utilization | Avoid staying near your limit all the time | Signals financial breathing room and control | A high available limit does not authorize recurring high spending |
The table is easier to understand when you focus on three signals: usage, payments, and whether your income matches your spending. If you use the card only in emergencies, the issuer has little behavior to evaluate. If you keep it maxed out, the account may suggest financial pressure. Regular use paired with a manageable bill usually gives the clearest picture.
A high limit isn’t an automatic reward for being a longtime customer. Your relationship with the institution can help, but the bank still reviews risk, spending patterns, and your ability to pay. A request is generally more likely to receive a favorable review when those signals point in the same direction.
Verification checklist before requesting an increase
- The card account shows updated income and the correct address, with no discrepancies between the app and your supporting documents.
- The card has been used recently for regular purchases, not just to test the limit.
- The bills from the past few months were paid by the due date, not just partially or late.
- The amount requested fits your reported income and the spending pattern the bank can already observe.
Frequently asked questions
How long does it take for the increased limit to appear after approval?
It depends on the issuer and the channel you used, but the new limit usually appears once the system completes its internal update. Sometimes that takes only a few minutes. In other cases, you may have to wait for the next processing cycle. If the app still shows the old limit, let the review finish before submitting the request again.
Can I request a credit limit increase while my bill is still outstanding?
Yes, you can request one, but approval becomes less likely when your credit utilization is high or your recent history makes you look riskier to the issuer. An outstanding bill by itself won't stop a review. The bank will look at how close you are to the limit and whether you've been making payments on time. Outdated income information can also weaken the application.
Does using the card infrequently help increase the limit?
It helps up to a point because it shows steady behavior, but barely using the card gives the issuer very little to assess. Reviews tend to go better when the issuer sees regular activity that matches your income and timely payments. If the card is rarely used, there may not be enough recent history to support a larger credit limit.
Are a credit limit increase and a temporary emergency increase the same thing?
No. An emergency increase is generally temporary and depends on the issuer's policy. A permanent increase changes the contractual credit limit. In practical terms, the emergency option covers a one-time need, but it doesn't give the card a permanently higher credit range.
What happens to my credit limit when I make a purchase in installments?
The purchase uses the corresponding amount of your credit limit as soon as it's approved, so your available balance drops right away. With many cards, that credit comes back gradually as you pay each installment, although the timing depends on how the institution manages the account. So if you make installment purchases without much room left, your available credit can stay tight for several months.
